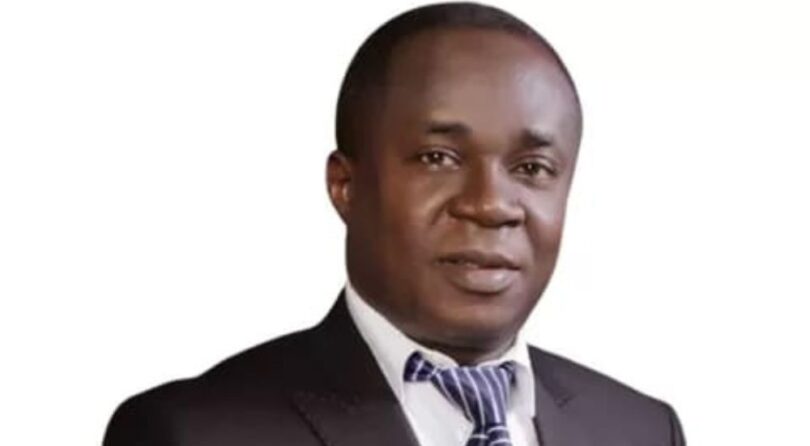
A financial expert, Prof. Uche Uwaleke, says the Central Bank of Nigeria’s Monetary Policy Committee may reduce the Monetary Policy Rate by 50 basis points at its September meeting.
Uwaleke who is the Director of the Institute of Capital Market Studies and President of Capital Market Academics of Nigeria, said this in an interview on Monday in Abuja, ahead of the 307th MPC meeting scheduled for Monday and Tuesday.
The MPC had retained the MPR, the benchmark interest rate, at 26.5 per cent at its 306th meeting in July.
The committee also maintained the standing facilities corridor at +50/-450 basis points around the MPR, while the Cash Reserve Ratio remained at 45 per cent for deposit money banks, 16 per cent for merchant banks and 75 per cent for non-Treasury Single Account public sector deposits.
Uwaleke said prevailing economic conditions could support a modest reduction in the benchmark rate, citing moderating inflation, exchange-rate stability, improved foreign exchange market liquidity and an increase in external reserves.
“I also see a mild rate cut against the backdrop of the recently signed Memorandum of Understanding between the Minister of Finance and the CBN governor on fiscal and monetary policy collaboration,” he said.
The expert also highlighted the recent MoU between the Federal Ministry of Finance and the CBN on fiscal and monetary policy coordination, describing the development as significant for economic management.
He said stronger coordination was necessary because government expenditure, borrowing, liquidity, exchange rates, inflation and private-sector credit were closely interconnected.
“For an economy in which government spending, public borrowing, liquidity conditions, exchange-rate movements, inflation and private-sector credit are deeply interconnected, the institutionalisation of regular policy coordination is both timely and economically significant.
“The MoU provides a framework for cooperation that goes beyond personal relationships between the Minister of Finance and the Governor of the CBN.
“It establishes structured mechanisms for information-sharing, aligned macroeconomic assumptions and the resolution of areas where fiscal and monetary actions might otherwise work at cross-purposes,” Mr Uwaleke said.
According to him, the cooperation between both authorities should eventually move beyond an administrative arrangement and become part of a more permanent institutional framework.
Uwaleke said the existing MoU could provide the basis for such coordination but argued that an arrangement of its economic importance should ultimately be supported by appropriate legislation.
“Nigeria could consider reviewing and, where appropriate, amending the relevant provisions of the CBN Act 2007 and other fiscal-governance legislation to establish a transparent framework for fiscal-monetary coordination.
“The framework should also clarify the respective responsibilities of the fiscal and monetary authorities, establish procedures for setting broad inflation objectives, and protect the CBN’s instrument and operational autonomy.
“Such legislation should not create a mechanism through which fiscal authorities can dictate monetary-policy decisions. Rather, it should codify the distinction between shared macroeconomic objectives and independent policy instruments,” he said.
He said fiscal and monetary authorities should retain their respective responsibilities while working together to ensure greater consistency in economic policy.
Uwaleke noted that fiscal authorities should remain responsible for taxation, public expenditure, fiscal policy and debt management, while the CBN should maintain the autonomy required to conduct monetary policy.
“At the same time, both institutions should be required to exchange information, publish relevant assumptions and explain publicly how their policies interact.
“The broader objective should be a coherent economic policy architecture in which monetary, fiscal, trade, financial and structural policies reinforce one another.
“Indeed, Nigeria’s current circumstances make this institutional question especially urgent.
“The country has made measurable progress in rebuilding macroeconomic stability, but inflation, financing costs, food and transport pressures, weak monetary transmission and the need for stronger private-sector credit continue to present difficult policy challenges.
“The CBN’s own 2026 outlook anticipates further disinflation and a lower interest-rate environment while recognising the importance of monetary conditions, fiscal operations and financial-market stability,” he said.
The MPC’s September meeting is expected to consider developments in inflation, foreign exchange market conditions, liquidity, economic activity and financial stability before determining its monetary policy stance.
Uwaleke’s comments come against the backdrop of ongoing efforts by monetary and fiscal authorities to balance inflation management, exchange-rate stability, economic growth and access to credit.
ENDS